SUBSCRIBE
Enter your Name and Email address to get
the newsletter delivered to your inbox.
Please include name of person that directed you to my online newsletter so I can thank them personally.
Tom Meaglia, ChFC®, AEP®,
CLU®, CRPC®, MSFS
Chartered Financial Consultant
Investment Advisor Representative
Chartered Retirement Planning Counselor
CA Insurance Lic. #0567507
Meaglia Financial Consulting
2105 Foothill Blvd., #B140, La Verne, CA 91750
Toll Free: 800-386-3700
Bus: 909-593-6105
Cell: 818-681-8600
Fax: 909-593-6120
Email: tom@meagliafinancialconsulting.com
Website: www.meagliafinancialconsulting.com
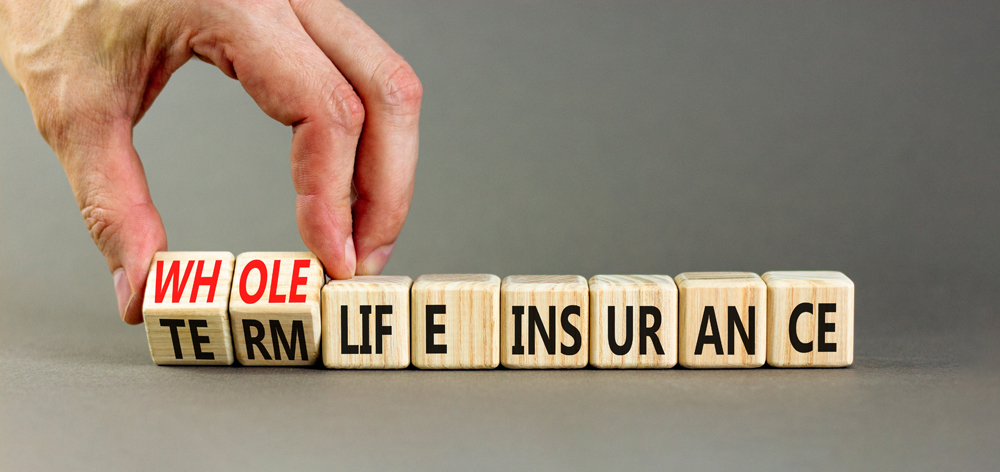
Will the Federal Reserve lower the federal funds rate this month? Probably not at the top of your mind—but it matters if you're deciding whether to buy whole life insurance.
Understanding how federal interest rates affect whole life insurance can help you make better policy decisions. Whole life insurance provides a death benefit and accumulates cash value, funded by a portion of your premiums. This cash value grows at a guaranteed minimum rate, though that rate and any additional returns are influenced by changes in the federal funds rate, affecting how much your cash value earns over time.
A fixed-premium policy lets you lock in that lower premium for life, while still delivering the same portfolio-hedging and retirement planning benefits that a whole life policy offers in any economy.
But remember, whole life insurance isn't primarily about cash value growth. Its guaranteed death benefit provides peace of mind regardless of market fluctuations. If you're treating the policy mainly as a savings vehicle, interest rates matter more; if your priority is providing for loved ones, fluctuating rates are less critical.
Enter your Name and Email address to get
the newsletter delivered to your inbox.
Please include name of person that directed you to my online newsletter so I can thank them personally.
Enter your Name, Email Address and a short message. We'll respond to you as soon as possible.
Thomas Meaglia is an Investment Adviser Representative of Coppell Advisory Solutions LLC, dba, Fusion Capital Management, a registered investment adviser that only conducts business in jurisdictions where it is properly registered, or is excluded or exempted from registration requirements. Registration as an investment adviser is not an endorsement of the firm by securities regulators and does not mean the adviser has achieved a specific level of skill or ability. The firm is not engaged in the practice of law or accounting.
Insurance and annuity products are not sold through Fusion Capital Management. Fusion does not endorse any annuity or insurance product, nor does it guarantee any insurance or annuity performance. Annuity and life insurance guarantees are subject to the claims-paying ability of the issuing insurance company. If you withdraw money from or surrender your contract within a certain time after investing, the insurance company may assess a surrender charge. Withdrawals may be subject to tax penalties and income taxes. Persons selling annuities and other insurance products receive compensation for these transactions. These commissions are separate and distinct from Fusion's investment advisory fees.
Meaglia Financial Consulting and LTM Marketing Solutions, LLC are unrelated companies. This publication was prepared for the publication’s provider by LTM Marketing Solutions, LLC, an unrelated third party. Articles are not written or produced by the named representative.
The information and opinions contained in this web site are obtained from sources believed to be reliable, but their accuracy cannot be guaranteed. The publishers assume no responsibility for errors and omissions or for any damages resulting from the use of the published information. This web site is published with the understanding that it does not render legal, accounting, financial, or other professional advice. Whole or partial reproduction of this web site is forbidden without the written permission of the publisher.